UAE VAT on Construction Contracts, Retention and Advance Payments
How UAE VAT applies to construction contracts — the date of supply on progress payments, why retention VAT falls due before you are paid, and how advances must be invoiced.
ERP Technology AdvisorPublished Updated 11 min read
Last updated: July 2026
VAT looks simple at 5 percent, until you apply it to a construction project. A single job can run monthly progress payments for two years, hold retention long after handover, and start with a mobilisation advance, and each of those has its own rule for when the tax becomes due. Get the timing wrong and you pay VAT out of your own pocket before the client pays you, or you face penalties from the Federal Tax Authority. This guide explains how UAE VAT applies to construction contracts, and how the right construction ERP for UAE contractors keeps it correct.
Is VAT charged on construction in the UAE?
Yes, construction services in the UAE are subject to VAT at the standard rate of 5 percent. This covers building works, civil and engineering services, project management, fit-out, and most related construction activities.
VAT has applied in the UAE since January 2018, and construction was standard-rated from the start. Whether the client is a developer, a business, or a government body, the contractor generally charges 5 percent VAT on their services.
The complexity is not the rate; it is the timing. Because construction contracts involve staged payments over long periods, the hard question is not how much VAT, but when it becomes due, which is where most contractors get caught out.
What is the UAE VAT law?
The UAE VAT law is set out in Federal Decree-Law No. 8 of 2017 on Value Added Tax and its Executive Regulations under Cabinet Decision No. 52 of 2017, administered by the Federal Tax Authority (FTA). It was significantly amended by Federal Decree-Law No. 18 of 2022, effective from January 2023.
Together these establish the 5 percent standard rate, the rules on when tax is due, invoicing requirements, and record-keeping obligations. The FTA also publishes sector-specific VAT guides, including for construction and real estate, that explain how the rules apply in practice.
For contractors, the most important parts of the law are the “date of supply” rules, which determine when VAT must be accounted for. You can read the VAT Decree-Law itself on the official UAE legislation portal, and this guide explains how it plays out on a real construction contract.
When is VAT due on a construction contract?
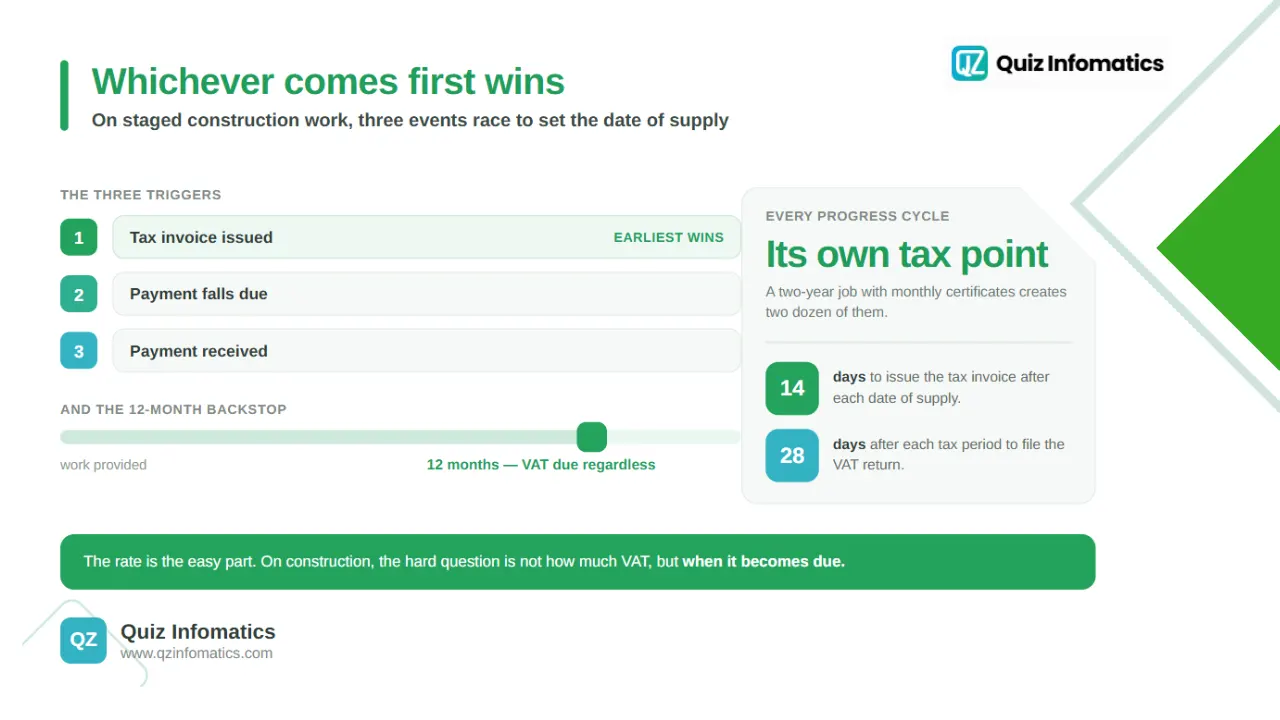
VAT on a construction contract is due at the “date of supply,” and for staged construction work that date is the earliest of the invoice date, the date payment is due, or the date payment is received. This is governed by the continuous-supply rules in the law.
Because construction is a continuous or periodic supply of services, a special rule applies. For contracts with periodic payments or consecutive invoices, the date of supply is triggered at the earliest of three events:
The date a tax invoice is issued
The date payment is due, as shown on the tax invoice
The date payment is actually received
There is also a backstop: if none of these occurs within 12 months of the work being provided, the date of supply is automatically triggered at that 12-month point. This stops VAT from being deferred indefinitely on long projects, and it means each progress cycle creates its own tax point.
How is VAT treated on progress and interim payments?
Each progress or interim payment on a construction contract triggers its own date of supply, so VAT must be accounted for on each one as it falls due. You cannot wait until the project ends.
In practice, every time you invoice for or are due a progress payment, a tax point arises, and VAT on that amount must be reported in the relevant VAT return. The law also requires a tax invoice to be issued within 14 days of the date of supply, a requirement extended to periodic supplies and consecutive payments from January 2023.
This ties VAT directly to your progress billing and interim payment certificates. Each certified interim payment carries VAT, which must be captured accurately and on time, across what may be dozens of payment cycles on a single project — which is what construction accounting software is for.
How is VAT treated on retention?
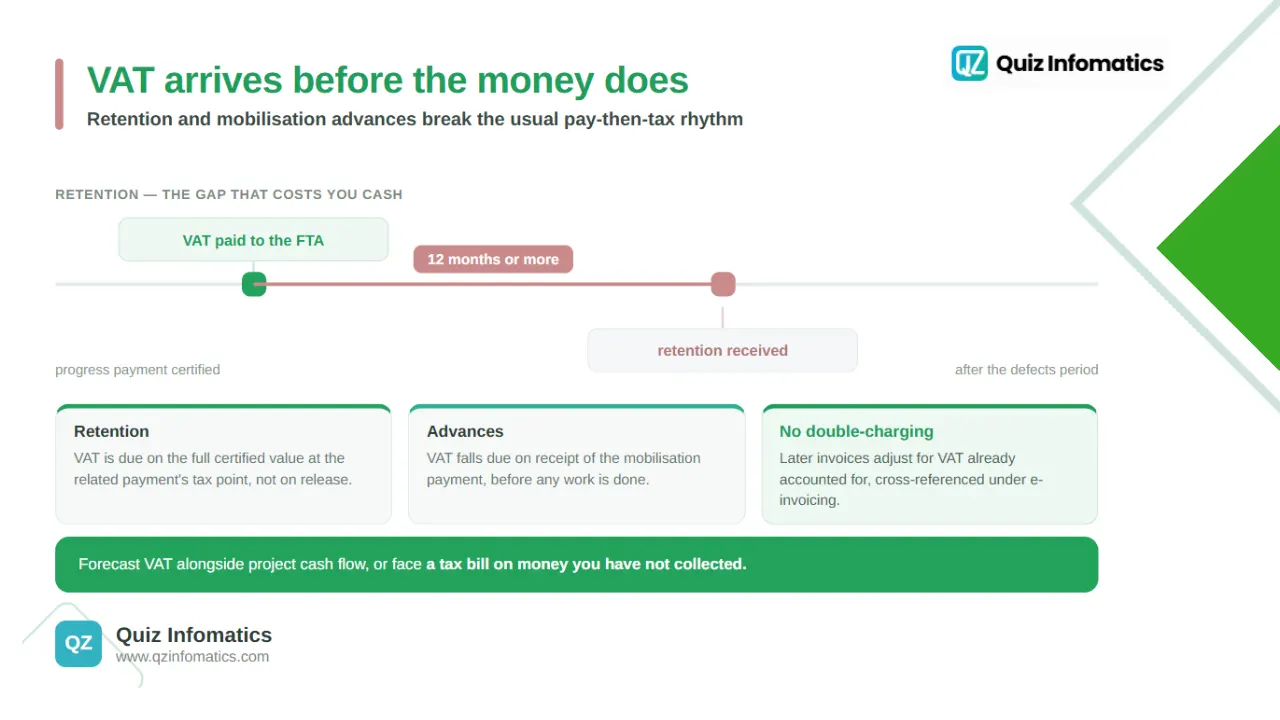
VAT on retention is due at the same time as the payment it relates to, not when the retention money is finally released. This is one of the most misunderstood, and most cash-flow-damaging, rules in construction VAT.
Retention is a portion of each progress payment held back as security, often released a year or more after the work. It would be natural to assume VAT on that retained amount is only due when the money is eventually paid, but that is not how the rules work. VAT is accounted for on the full certified value, including the retained portion, at the tax point of the related progress payment.
The consequence is significant: a contractor effectively pays VAT to the FTA on retention money they have not yet received and will not receive for many months. Understanding and planning for this is essential, and it links directly to how variation orders and retention are managed on the contract. Under the incoming e-invoicing rules, the eventual retention release generates its own tax document that references the earlier invoices, so the VAT is not double-counted.
How is VAT treated on advance and mobilisation payments?
VAT on an advance or mobilisation payment is due when the payment is received, and a tax invoice must be issued for the advance at that time. You cannot defer it to the first progress milestone.
Mobilisation advances are standard in UAE construction, paid up front so the contractor can establish the site. Because receiving payment is one of the events that triggers the date of supply, VAT becomes due as soon as the advance is received, even before any work is done.
The contractor must issue a tax invoice for the advance and report the VAT in that period. Later progress invoices then cover only the remaining balance and are adjusted for the VAT already accounted for on the advance, so the same VAT is never charged twice. Failing to invoice the advance correctly, or charging VAT again on the full value at final invoicing, is a common and costly error.
VAT and e-invoicing on construction
VAT and the UAE’s new e-invoicing system are closely linked, because e-invoicing changes how construction tax invoices, including for retention and advances, must be issued and reported. Contractors need their systems ready for both.
As the UAE rolls out mandatory structured e-invoicing, progress bills, retention releases, and advance invoices must all be issued as compliant e-invoices and reported to the FTA in near real time. Advances and retention carry specific rules: the advance invoice and the eventual retention invoice must reference the related progress invoices so the FTA can trace that VAT was correctly accounted for.
This is a major system requirement. A contractor whose software cannot handle VAT correctly across progress, retention, and advances will struggle to produce compliant e-invoices.
What about zero-rating and exemptions?
Most construction is standard-rated at 5 percent, but the first supply of a new residential building is zero-rated, and some property transactions are exempt. Knowing the difference matters for how VAT is charged and recovered.
The key distinctions are:
Construction services. Standard-rated at 5 percent, regardless of the building type.
First supply of a new residential building. Zero-rated, if made within the first three years of completion and subject to conditions.
Subsequent supplies of residential property. Generally exempt.
Commercial property. Standard-rated at 5 percent.
Bare land. Exempt.
For mixed-use projects, such as a building with both retail and residential units, contractors must apportion their input VAT and can only recover the portion relating to taxable supplies. This apportionment is a common area of FTA scrutiny.
Can contractors recover input VAT on construction costs?
Yes, VAT-registered contractors can generally recover the input VAT they pay on construction costs, provided those costs relate to taxable supplies and are supported by valid tax invoices. This is a core benefit of the VAT system.
Input VAT on materials, subcontractors, plant, and other project costs can usually be reclaimed, offsetting the output VAT charged to clients. However, recovery depends on holding compliant tax invoices, and a non-compliant supplier invoice missing mandatory fields can block the claim.
Where a contractor makes a mix of taxable and exempt supplies, input VAT must be apportioned. Getting this right protects both cash flow and compliance, and it is another reason accurate VAT records matter so much on construction projects.
Tax invoices, records, and returns
UAE VAT law requires tax invoices to be issued within 14 days of the date of supply, records to be kept for at least five years, and VAT returns to be filed within 28 days of each tax period. Construction’s payment complexity makes this administratively heavy.
A compliant tax invoice must carry all the mandatory fields, and it must be issued within 14 days of each tax point, which on construction means within 14 days of each progress period. VAT records must be retained for five years (seven for corporate tax purposes), and under e-invoicing, electronic invoices must be stored and retrievable for the FTA.
VAT returns are due 28 days after the end of each tax period, monthly for large taxpayers and quarterly for most businesses. Across many projects and payment cycles, keeping all of this accurate by hand is a serious challenge.
Let’s talk about your businessStart with a free 30 minute call. We’ll ask the right questions, listen carefully, and give you an honest view of what’s possible.
The biggest practical issue with construction VAT is cash flow, because VAT often becomes due before the contractor has actually been paid. This is a real and recurring strain.
The retention rule is the clearest example: VAT is payable on retention money months or years before it is received. Advance payments, timing mismatches between VAT due dates and client payment dates, and slow input VAT recovery all add to the pressure. On a large project, the VAT timing alone can create significant working-capital gaps.
Managing this well means forecasting VAT alongside the project’s cash flow, so the business is never surprised by a VAT bill on money it has not yet collected. This is exactly the kind of visibility a connected project costing and accounting system provides.
Common VAT mistakes on construction contracts
The most common construction VAT mistakes involve mis-timing the tax, especially on retention and advances. Each one risks penalties or lost cash.
Frequent errors include:
Deferring VAT on retention until release, when it is due with the related payment.
Missing VAT on advances, or double-charging VAT at final invoicing.
Late tax invoices, breaching the 14-day rule on progress payments.
Wrong rate on property, confusing residential zero-rating with standard-rated services.
Each of these stems from the same root: construction’s payment complexity overwhelming manual VAT processes. The fix is a system that applies the correct date of supply and VAT treatment automatically.
How construction ERP handles VAT on construction contracts
A construction ERP handles construction VAT by applying the correct date of supply to every progress payment, retention amount, and advance, generating compliant tax invoices and feeding accurate VAT returns. It removes the manual timing errors that cause penalties.
In a well-configured system, each progress bill triggers VAT at the right tax point, VAT on retention is accounted for with the related payment, advances are invoiced correctly and adjusted at final billing, and everything flows into VAT-return-ready records. As e-invoicing arrives, the same system produces the compliant, cross-referenced e-invoices the FTA requires.
This is central to modern contractor accounting software. Platforms such as Odoo, configured for UAE construction and VAT, can bring billing, retention, advances, and tax together, and a well-run ERP implementation is what makes that compliance reliable.
VAT on construction across the GCC
VAT applies to construction across most of the GCC, though the rate and specific rules vary by country. Contractors working regionally need to handle each market separately.
The UAE, Bahrain, and Oman apply VAT, with the UAE at 5 percent, while Saudi Arabia raised its VAT rate to 15 percent in 2020. Each country has its own tax authority, date-of-supply rules, and invoicing requirements, and Saudi Arabia is further advanced in mandatory e-invoicing through ZATCA.
For contractors operating in more than one GCC market, a system that can apply each country’s VAT rules correctly, while managing the same underlying construction payment structures, is a real advantage. If you want to check a figure quickly, the UAE VAT calculator adds or removes 5 percent and shows the working.
How QZ Infomatics helps contractors
Getting construction VAT right comes down to applying the correct tax treatment automatically across progress, retention, and advances, connected to your billing and returns. That accuracy protects both compliance and cash flow.
A practical step is to manage VAT in the same system as your progress billing, retention, and budgets, so the date of supply is applied correctly, tax invoices are compliant and on time, and VAT is forecast alongside cash flow. This turns VAT from a compliance risk into a controlled, predictable part of the business.
If you would like help with that, our construction ERP software for UAE contractors brings VAT, billing, retention, BOQ, cost control, and budgeting into one platform, built for how contracting businesses actually work.
UAE VAT on construction, in a nutshell
To recap the essentials:
Construction services in the UAE are standard-rated at 5 percent under Federal Decree-Law No. 8 of 2017 and its amendments.
The date of supply for staged construction is the earliest of the invoice date, the payment-due date, or the date of receipt, with a 12-month backstop.
Retention VAT is due with the related payment, not when retention is released, so contractors pay VAT before receiving the money.
Advance payments trigger VAT on receipt, and must be invoiced and later adjusted to avoid double-charging.
A construction ERP applies these rules automatically and produces the compliant tax invoices, and e-invoices, the FTA requires.
Construction VAT is deceptively complex, and its timing rules can quietly drain a contractor’s cash if mishandled. Applying the correct treatment automatically, in one connected system, is one of the most valuable safeguards a UAE contractor can put in place.
About the author
QZ Infomatics Construction Technology Team — QZ Infomatics is a Dubai-based ERP and IT consultancy in Business Bay that implements construction and contracting software across the UAE and GCC. The team helps contractors apply correct VAT treatment across progress billing, retention, and advances, connected to their accounting and returns, drawing on hands-on experience with construction ERP for UAE projects. This guide reflects that practical experience helping contracting businesses stay compliant and protect their cash flow.
This article is general information, not tax or legal advice. VAT rules, rates, and treatments can change, so confirm your specific obligations with the Federal Tax Authority or a qualified tax adviser.
Share this article
Frequently asked questions
UAE construction VAT questions
Is VAT charged on construction in the UAE?
Yes. Construction services in the UAE are subject to VAT at the standard rate of 5 percent, covering building works, engineering, project management, and most related activities, under the UAE VAT law.
When is VAT due on a construction contract?
VAT is due at the date of supply, which for staged construction is the earliest of the tax invoice date, the date payment is due, or the date payment is received, with a backstop 12 months after the work is provided.
How is VAT treated on retention in construction?
VAT on retention is due at the same time as the payment it relates to, not when the retention is released. This means contractors account for VAT on retained amounts before actually receiving that money.
How is VAT treated on advance payments?
VAT on an advance or mobilisation payment is due when the payment is received, and a tax invoice must be issued for the advance at that time. Later invoices are adjusted so the VAT is not charged twice.
What is the VAT rate on construction in the UAE?
Construction services are standard-rated at 5 percent. The first supply of a new residential building is zero-rated under conditions, while commercial property is standard-rated and some property transactions are exempt.
Can contractors recover input VAT on construction costs?
Yes, VAT-registered contractors can generally recover input VAT on costs relating to taxable supplies, provided they hold valid tax invoices. Input VAT must be apportioned where supplies are a mix of taxable and exempt.
How long do construction VAT records need to be kept?
VAT records must be kept for at least five years, and seven years for corporate tax purposes. Under e-invoicing, electronic invoices must be stored and remain retrievable for the FTA.
Does e-invoicing affect construction VAT?
Yes. Progress bills, retention, and advance invoices must be issued as compliant e-invoices and reported to the FTA, with retention and advance documents referencing related invoices so VAT is correctly traced and not double-counted.
Continue reading
Related articles
Construction & Contracting
Labour Camp and Manpower Cost Allocation for GCC Contractors
How GCC contractors allocate labour camp, accommodation and manpower costs across active projects — from WPS payroll to project cost in ERP.
ERP Technology Advisor · 16 August 2026 · 11 min read
Book a free 30 minute call with QZ Infomatics in Dubai. You will leave it with a platform recommendation, the reasoning behind it, a realistic timeline and an indicative budget band — before you commit to anything.
✓ A consultant who delivers projects, not a sales desk
✓ Odoo, Microsoft Dynamics 365 and Oracle NetSuite compared honestly
✓ Licence cost and implementation cost quoted as separate numbers
✓ If we are not the right fit for you, we will say so