What is earned value management?
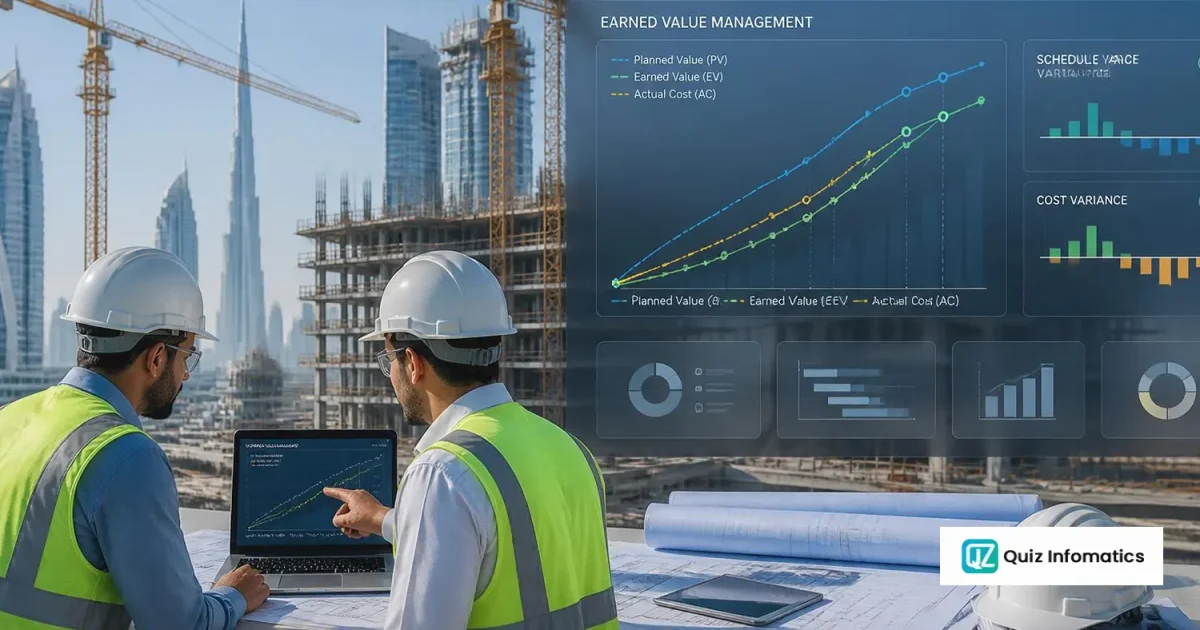
Earned value management is a technique for measuring project performance by comparing three numbers: what you planned to have spent by now, what you have actually spent, and what the work you have completed was worth.
That third number is the one most projects do not have, and it is what makes the technique work.
Consider a project six months in, budgeted at AED 10 million, that has spent AED 5 million. Is it on track?
You cannot say. Spending half the budget in half the time looks reasonable — but only if half the work is done. If a third of the work is done, the project is heading for AED 15 million. If two-thirds is done, it is heading for AED 7.5 million and will finish under budget.
Cost alone tells you nothing about performance. Progress alone tells you nothing about cost. EVM combines them, and it produces a forecast rather than a report.
That is the practical value. Traditional cost reporting is retrospective — it tells you what happened last month. Earned value is predictive. At 20% complete, with reasonably stable performance, it produces a forecast of final cost that is usually more reliable than anyone’s judgement, and it produces it early enough to act on.
The three measurements
Everything in EVM derives from three figures.
Planned value (PV)
The budgeted cost of the work scheduled to be complete by now.
Also called the budgeted cost of work scheduled. It comes from the time-phased budget — the project budget spread across the schedule, so at any date you can say what should have been achieved and what it was budgeted to cost.
Example: by the end of month six, the plan says the substructure and two floors of frame are complete, budgeted at AED 4,000,000. PV = AED 4,000,000.
Earned value (EV)
The budgeted cost of the work actually completed.
The central concept. It values what has been built at budget rates, not at what it cost. This is what separates EVM from ordinary cost reporting and it is the point people find counter-intuitive on first encounter.
Example: by month six, the substructure and one and a half floors are complete. That scope was budgeted at AED 3,400,000. EV = AED 3,400,000 — regardless of what was actually spent achieving it.
Actual cost (AC)
What has genuinely been spent on the work completed.
From the cost ledger. On a construction project this must include committed cost — purchase orders issued and subcontracts awarded but not yet invoiced. Using invoices only understates actual cost by four to six weeks of procurement, which produces a flattering and wrong cost performance figure.
Example: AED 3,900,000 spent and committed. AC = AED 3,900,000.
Variances
Schedule variance (SV)
SV = EV - PV
Example: 3,400,000 − 4,000,000 = −AED 600,000
Negative means behind schedule. The project has earned AED 600,000 less value than the plan called for.
Note that schedule variance is expressed in money, not time. This confuses people initially. It says the project is AED 600,000 of work behind, not that it is six weeks late. Converting to time requires the schedule.
Cost variance (CV)
CV = EV - AC
Example: 3,400,000 − 3,900,000 = −AED 500,000
Negative means over budget. The project spent AED 3,900,000 to produce work worth AED 3,400,000 — an over-run of AED 500,000 on work completed to date.
Cost variance is the more serious of the two. Schedule variance can often be recovered by acceleration. Cost variance is money already spent, and on most projects it is a reliable indicator of the rate at which the rest of the work will over-run too.
Variances are absolute. Indices are ratios, which makes them comparable across projects of different sizes and — crucially — usable for forecasting.
Schedule performance index (SPI)
SPI = EV / PV
Example: 3,400,000 ÷ 4,000,000 = 0.85
Below 1.0 means behind schedule. At 0.85, the project is achieving 85% of planned progress.
Cost performance index (CPI)
CPI = EV / AC
Example: 3,400,000 ÷ 3,900,000 = 0.87
Below 1.0 means over budget. At 0.87, every dirham spent is producing 87 fils of budgeted value.
CPI is the single most useful number in EVM. Research across large project datasets has consistently found that CPI stabilises early — typically by around 20% complete — and rarely improves materially thereafter. A project running at 0.87 at 20% complete will most likely finish near 0.87.
That finding is the whole argument for EVM. It means a defensible forecast of final cost is available at 20% complete, when there is still time to change something, rather than at 80% when there is not.
Forecasting
Where EVM stops being a report and becomes a decision tool.
Estimate at completion (EAC)
Three methods, for three different situations.
Method 1 — performance continues as it has
EAC = BAC / CPI
Example, with a budget at completion of AED 10,000,000: 10,000,000 ÷ 0.87 = AED 11,494,000
The default and usually the most reliable, because CPI stabilises. Use this unless you have a specific reason not to.
Method 2 — the over-run was a one-off
EAC = AC + (BAC - EV)
Example: 3,900,000 + (10,000,000 − 3,400,000) = AED 10,500,000
Assumes the remaining work runs to budget. Legitimate where the variance had an identifiable, non-recurring cause. Frequently used as wishful thinking, so it requires justification.
Method 3 — schedule pressure will make it worse
EAC = AC + [(BAC - EV) / (CPI x SPI)]
Example: 3,900,000 + [6,600,000 ÷ (0.87 × 0.85)] = AED 12,825,000
The most pessimistic, and appropriate where recovering the schedule will require acceleration — overtime, additional resources, expedited procurement — that costs money.
Run all three. The spread between them is itself information: a wide spread means the outcome is genuinely uncertain and the forecast needs a range rather than a point.
Estimate to complete (ETC)
ETC = EAC - AC
Example: 11,494,000 − 3,900,000 = AED 7,594,000 — what the remaining work will cost, and the number the cash flow forecast needs.
Variance at completion (VAC)
VAC = BAC - EAC
Example: 10,000,000 − 11,494,000 = −AED 1,494,000
The forecast final over-run. This is the headline number for management — not the current variance, but where the project is heading.
To-complete performance index (TCPI)
TCPI = (BAC - EV) / (BAC - AC)
Example: (10,000,000 − 3,400,000) ÷ (10,000,000 − 3,900,000) = 6,600,000 ÷ 6,100,000 = 1.08
The efficiency required for the remainder to still hit budget. At 1.08, the project must run 8% better than budget for the rest of its life — having so far run 13% worse.
TCPI is the reality check. Where TCPI exceeds CPI by more than about 10%, recovery to budget is not realistic, and the honest response is to re-baseline rather than to report a recovery plan nobody believes.
Worked example, in full
A UAE fit-out contract. Budget at completion AED 10,000,000. Six months into a twelve-month programme.
Planned value, earned value and actual cost for the worked example
| Measure |
|
Value |
| Planned value |
PV |
AED 4,000,000 |
| Earned value |
EV |
AED 3,400,000 |
| Actual cost (incl. committed) |
AC |
AED 3,900,000 |
Earned value metrics for the worked example, with formula, result and reading
| Metric |
Formula |
Result |
Reading |
| Schedule variance |
EV − PV |
−600,000 |
Behind |
| Cost variance |
EV − AC |
−500,000 |
Over budget |
| Schedule performance index |
EV ÷ PV |
0.85 |
85% of planned progress |
| Cost performance index |
EV ÷ AC |
0.87 |
87 fils of value per dirham |
| Estimate at completion |
BAC ÷ CPI |
11,494,000 |
Forecast final cost |
| Estimate to complete |
EAC − AC |
7,594,000 |
Remaining spend |
| Variance at completion |
BAC − EAC |
−1,494,000 |
Forecast over-run |
| To-complete index |
(BAC−EV)÷(BAC−AC) |
1.08 |
Must run 8% better than budget |
The reading. The project is 34% complete against a plan of 40%, and it is spending faster than it is building. Forecast over-run is roughly AED 1.5 million — 15% of the contract value. Recovery to budget requires the remaining work to run 8% better than budgeted, having run 13% worse so far.
At six months, that is actionable. In the monthly accounts, the same project shows AED 3.9 million spent against a AED 10 million budget, which looks entirely comfortable. The accounts are not wrong. They are just not answering the question.
The project profitability calculator on this site runs the same arithmetic from committed cost, if you want to try it against a live job.
Measuring percentage complete — where EVM lives or dies
Everything above depends on earned value, and earned value depends on knowing how much work is genuinely complete. Get this wrong and every number is decorative.
Methods for measuring percentage complete, and when each one applies
| Method |
How |
Use when |
| Units complete |
Physical quantity done ÷ total quantity |
Repetitive measurable work — most construction. The best method. |
| Milestone / weighted |
Credit at defined milestones |
Discrete deliverables with clear completion points |
| 0/100 |
No credit until finished |
Short work packages within one reporting period |
| 50/50 |
50% at start, 50% at completion |
Short packages, smooths reporting |
| Cost incurred |
Cost to date ÷ forecast cost |
Last resort only |
| Level of effort |
Progress equals time elapsed |
Management, supervision, site running costs |
Never let cost drive progress on the whole project. Using cost incurred as the measure of progress makes EV = AC by definition, CPI = 1.00 always, and the entire technique produces nothing. It is circular. It is also the most common way EVM gets implemented badly, because it requires no additional measurement — which is exactly why it is tempting.
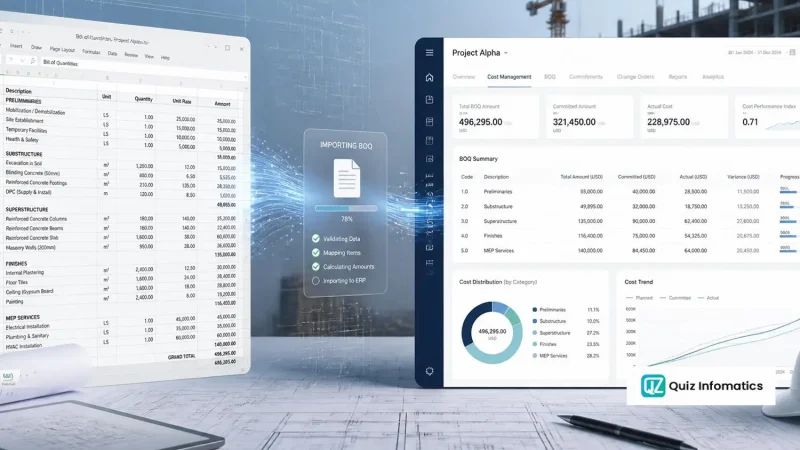
Estimated percentages drift optimistic. Ask a site engineer how complete something is and the answer trends high, consistently and without dishonesty. Measured quantities do not have that bias. On construction projects the BOQ provides measurable units for most of the work, which is why BOQ-driven progress measurement is materially more reliable than judgement.
EVM in UAE construction
Three practical adaptations.
Committed cost must be in actual cost. Non-negotiable. A contractor whose AC includes only invoices received is calculating CPI on a cost base four to six weeks out of date, during a period when procurement typically runs ahead of delivery. The resulting CPI is flattering and wrong. This is what project costing software is for.
Variations complicate the baseline. An approved variation order changes the budget at completion, and BAC must be updated or every metric becomes meaningless. Submitted-but-unapproved variations must stay out of BAC — including them recognises revenue on work that may never be paid for. Track them separately as upside.
Preliminaries are level of effort. They accrue with time, not with production. Measuring them by any other method distorts the whole picture, because on a delayed project preliminaries continue while earned value does not.
On payment applications: earned value and certified value are different numbers, and the difference is over- or under-billing. A contractor billing ahead of earned value has better cash flow than performance, which is worth knowing before the client’s QS notices. Construction accounting software that holds both figures makes the gap visible monthly.
What EVM does not tell you
It does not measure quality. A project can be on budget and on schedule and building the wrong thing to a poor standard. EV records that work was done, not that it was done well.
It does not distinguish critical from non-critical work. SPI of 0.95 might mean minor slippage on non-critical items, or a serious delay on the critical path. SPI is not a substitute for schedule analysis — read it alongside the programme, not instead of it.
SPI becomes unreliable near completion. As a project finishes, EV converges on PV and SPI tends to 1.00 regardless of how late the project is. A project that finishes six months late shows SPI of 1.00 on its final day. Beyond about 80% complete, use the schedule for schedule performance.
It is only as good as the baseline. A padded budget produces CPI above 1.00 on a badly run project. A baseline that has been quietly revised makes comparison meaningless.
It cannot tell you why. EVM identifies that a control account is over-running. It does not say whether that is a rate problem, a productivity problem, a scope problem or a measurement error. That still requires someone to go and look.
Implementing EVM
1. Build a proper WBS. EVM is calculated at control account level, so it requires a work breakdown structure with control accounts and owners. Without one, there is nothing to calculate against.
2. Time-phase the budget. The budget must be spread across the schedule to produce planned value at any date. This is where a shared cost code structure between the ERP and Primavera P6 becomes necessary rather than merely convenient.
3. Choose and document a progress method per control account. Units complete wherever possible. Write it down, so the method does not drift between reporting periods.
4. Capture actual cost including commitment, coded to the same control accounts.
5. Baseline and freeze. Then control changes to it formally.
6. Report monthly, at control account level. Project-level EVM tells you there is a problem. Control account EVM tells you where.
7. Act on it. EVM that produces a report nobody responds to is an expensive way to document failure.
The system requirement: EVM needs budget, commitment, actual cost and progress in one structure. Assembling it monthly in Excel is possible and it is what most UAE contractors do — which is why it happens quarterly at best, and why the number is three weeks old when it arrives. Construction ERP software in the UAE produces these figures continuously because all four inputs already live in the same place.
Part of our complete guide to ERP for construction.