What is a variation order?
A variation order is a formal instruction to change the works after the contract has been signed — adding scope, omitting scope, or altering the quality, sequence or timing of what was agreed.
It is the contract’s own mechanism for change. Construction contracts are signed before the work is fully understood, and every substantial project varies. The variation order is what makes change lawful and payable rather than a breach of contract by whoever decided to do something different.
Two things follow from that definition, and both matter more than they first appear.
A variation is an instruction, not a negotiation. Under most standard forms the employer or engineer has the right to instruct a change and the contractor is obliged to carry it out. The disagreement, if there is one, is about valuation — not about whether the work happens.
A variation is only a variation if the contract says it is. Work the contractor was already obliged to do under the original scope is not a variation, however inconvenient. This is the boundary that most variation disputes are actually about.
Why variations happen
Rarely because someone changed their mind. The recurring causes in the UAE market:
Design development. The contract is signed on drawings that are not fully coordinated. Detailed design resolves clashes, and the resolution changes the works.
Authority requirements. Dubai Municipality, Civil Defence, DEWA or a master developer imposes a requirement that was not in the tender documents.
Site conditions. Ground conditions, existing services, adjacent structures. What was found is not what was assumed.
Employer changes. A genuine change of requirement — a different tenant, a revised operating model, a specification upgrade.
Value engineering. Cost reduction after award, which is a variation in the opposite direction and is frequently forgotten in the register.
Errors and omissions. Something was missing from the drawings or the specification. Whose risk that is depends entirely on the contract type.
Coordination between packages. The MEP subcontractor needs a builder’s work opening that nobody measured.
The point of listing them: most variations are not the contractor’s doing and most are foreseeable in category if not in detail. A project with no variation register is not a project without variations. It is a project where nobody is recording them.
FIDIC Clause 13
Most substantial UAE contracts are FIDIC-based, and Clause 13 — Variations and Adjustments is where the variation machinery sits.
Clause 13 sets out the essentials:
- Who may instruct. The Engineer, generally, subject to any limits in the Particular Conditions
- What may be varied. Quantities, quality, levels, positions and dimensions, omissions, additional work, changes to sequence or timing
- Form of instruction. Generally written; oral instructions require confirmation
- The contractor’s right to object in defined circumstances — where materials are not readily obtainable, for example
- How variations are valued — the hierarchy below
- Value engineering, allowing the contractor to propose changes that reduce cost or improve the works
- Adjustments for changes in legislation and, where Sub-Clause 13.8 is active, for changes in cost through indexed formulae
One practical warning on 13.8. The cost adjustment mechanism is frequently deleted or left inactive in Middle East FIDIC contracts. Where that has happened, the contractor carries market price escalation with no contractual route to relief — which matters on long projects in a volatile materials market. Check whether it is live before assuming it protects you.
Clause 20 handles claims, and the interaction between the two is where a great deal of commercial argument happens. A variation instructed under Clause 13 with a time impact usually requires a Clause 20 claim as well.
Not sure whether your contract is lump sum or re-measurable?That one distinction decides whether a variation is payable at all. Thirty minutes with a consultant will tell you where you stand before you price the next instruction.
UAE law: the lump-sum problem
This is where UAE practice diverges from the printed form, and it is the most commercially significant section of this guide.
Construction contracts in the UAE are muqawala contracts, governed by a specific block of Civil Code provisions in addition to whatever the contract says.
The provision that matters: on a lump-sum contract based on an agreed design, the contractor has no claim to an increase in price for executing that design. This was Article 887 of the 1985 Civil Transactions Law and sits at Article 829 in the recodified law. The principle has been applied consistently by the UAE courts, including at Court of Cassation level.
What that means in practice.
Most UAE construction contracts are lump sum. Under a lump-sum contract, a contractor who discovers that the agreed design costs more than tendered has no statutory route to more money. Quantity errors, underestimated complexity, buildability problems in the employer’s design — none of those generate an entitlement by themselves.
The exception is a genuine variation instructed by the employer. The provision permits an increase where the contract provides for it or where the change results from a clear variation or addition instructed by the employer. Where the contract is silent on remuneration for additional works, the contractor is entitled to fair remuneration plus the value of materials supplied.
And there is the commercial trap. A contractor who builds a change first and prices it afterwards, on a lump-sum contract, with no instruction on record, is financing the change out of its own margin — and the statutory position offers no help.
Where the contract is re-measurable rather than lump sum, the position is different: quantities are remeasured on completion and the contractor is paid for what was actually built at the agreed rates.
Two further points worth knowing.
Hardship. The Civil Code provides a narrow judicial discretion to reduce an oppressive obligation in exceptional, unforeseeable circumstances — Article 249 in the old law, Article 224 in the new. The threshold set by the courts is demanding, and the provision permits reduction of an obligation rather than an increase in remuneration. It is not a route to recovering cost escalation.
Decennial liability. Separate from variations but relevant to any discussion of UAE construction law — contractors and designers carry a mandatory ten-year liability for structural defects that cannot be contracted out of.
How variations are valued
Most standard forms apply a hierarchy, and the order matters commercially.
1. Contract rates, where the varied work is of the same character and executed under similar conditions.
The cheapest and least contentious route. If the BOQ has a rate for 200 mm blockwork and the variation is more 200 mm blockwork, that rate applies.
This is the strongest practical argument for a well-structured BOQ with a wide range of rates. A bill with granular rates covering many item types gives the parties an objective basis for pricing most variations. A coarse bill forces negotiation on nearly everything.
2. Adjusted contract rates, where the work is similar but conditions differ.
The rate exists but the circumstances have changed — same blockwork, but at height, or in a confined area, or out of sequence. The rate is adjusted for the difference. Reasonable in principle, argumentative in practice, and the adjustment is where quantity surveyors earn their fees.
3. New rates, built from first principles.
Where nothing analogous exists. Cost of labour, plant and materials, plus overhead and profit at contractual percentages. Requires a proper build-up and full supporting detail.
4. Dayworks.
Time and materials at the schedule of daywork rates. The most expensive route for the employer and the most administratively burdensome for the contractor, because it requires signed daily records of labour, plant and materials. Signatures not obtained on the day are extraordinarily difficult to obtain later.
Where an omission is instructed, the same hierarchy applies in reverse, and the contractor may have a legitimate argument that omitting work leaves preliminaries and overhead under-recovered.
Notice, instruction and the record
The commercial reality behind every variation claim.
Most UAE contracts require written instruction. Tribunals take that requirement seriously. A contractor proceeding on a verbal instruction is in a materially weaker position than one holding a written one.
But not absolutely. Where an employer instructs orally, watches the varied work proceed and takes the benefit of it, arguments from good faith and unjust enrichment can carry an unpriced variation. That is a rescue argument, not a strategy. The record beats the doctrine, reliably and cheaply.
The records that support a variation claim, and what each one is for
| Document |
Purpose |
| The instruction |
Written, dated, referencing the change |
| Notice of intention to claim |
Within the contractual period — often short |
| Confirmation of verbal instruction |
Sent promptly where the instruction was oral |
| Quotation or estimate |
Where the contract requires one before proceeding |
| Approval |
Or a record of the employer’s failure to respond |
| As-executed records |
Photographs, dated, showing the work in place |
| Daywork sheets |
Signed on the day, where dayworks apply |
| Cost records |
Labour, plant, material, subcontract against the variation |
| Time impact |
Where the variation affects the programme |
Contemporaneous is the operative word. A record made at the time carries far more weight than one assembled during a dispute eighteen months later, and both a tribunal and an opposing QS can tell the difference immediately.
This is where document control software does real commercial work rather than administrative work. A register showing what was instructed, when, by whom, and what response was received — maintained as the project runs — is the evidence base for the entire variation account.
Approved, submitted, anticipated
Three states, and confusing them causes both commercial and accounting problems.
How approved, submitted and anticipated variations are treated in revenue and in the cost forecast
| State |
Meaning |
Revenue treatment |
In the cost forecast? |
| Approved |
Instructed and valued, agreed by the employer |
Recognise |
Yes |
| Submitted |
Claimed, not yet agreed |
Do not recognise |
Yes — the cost is real |
| Anticipated |
Expected but not yet claimed |
Do not recognise |
Yes, as an allowance |
The asymmetry is the point, and it is what auditors look for.
Cost is certain. The moment varied work is executed, the labour, plant and material have been consumed. That cost belongs in the forecast regardless of whether anyone has agreed to pay for it.
Revenue is not certain. A submitted variation may be rejected, reduced, or settled at final account for a fraction of the claim. Recognising it as revenue before agreement overstates margin.
Getting this wrong in either direction causes problems. Recognising unapproved variations as revenue produces a margin that evaporates at final account. Excluding their cost from the forecast understates the over-run and produces an earned value picture that is wrong in exactly the flattering direction.
The correct treatment: all variation cost in the forecast; only approved variation revenue in the accounts; submitted variations tracked separately as upside. Construction accounting software that holds variations with their own status and value is what makes this workable at scale.
Why variations go unbilled
Unbilled variations are the largest single source of margin loss in UAE contracting. Not disputed variations — unbilled ones. Work that was instructed, executed, and never claimed.
Five reasons, and none involves the client refusing to pay.
The instruction was verbal and nobody confirmed it. Site got told to do something, site did it. No paper.
Notice periods expired. Many contracts require notice within a short window. Miss it and entitlement can be lost regardless of merit.
The cost was never separated. Varied work was executed alongside contract work by the same gang and coded to the same cost code. When the claim is prepared, nobody can say what the variation cost.
The site knew and the commercial team did not. A site engineer treats an instruction as part of the job. It never reaches the person who prices claims.
It was too small to bother with. Individually true. Forty of them across a project is a different number.
The common factor is process, not entitlement. Every one of these is a record-keeping failure, and every one is preventable at close to zero cost. On a project with an active variation register, an instruction is logged the day it is received and the register is reviewed weekly. That single discipline recovers more margin than any commercial negotiation.
Let’s talk about your businessStart with a free 30 minute call. We’ll ask the right questions, listen carefully, and give you an honest view of what’s possible.
Managing variations properly
Maintain a live register. Every variation, its status, value, date instructed, date claimed, date approved, and cost incurred. Reviewed weekly with site and commercial in the same conversation.
Log first, price later. The instruction goes on the register the day it arrives. Valuation follows. A register that only records priced variations records too late.
Code variation cost separately. A distinct cost code, or a variation flag on the existing code, so cost against a variation is separable from cost against original scope. Without this, valuation from first principles is guesswork, and project costing software cannot help you.
Track the time impact alongside the cost. Variations that affect the programme generate prolongation cost, and that is a Clause 20 claim, separate from the Clause 13 valuation.
Assess the effect on the whole. A single variation may be modest. Their cumulative effect on programme, sequence and productivity can exceed the sum of individual valuations, and that disruption argument is far stronger when it is supported by a complete register.
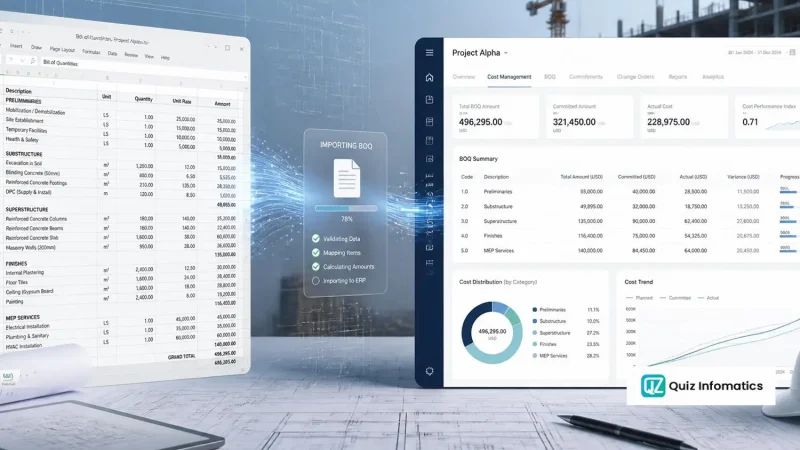
Link variations to the BOQ and the cost structure. A variation priced from contract rates, coded to the BOQ line it affects, updating the budget at completion — that is the chain, and it only works if the work breakdown structure and cost codes were set up to carry it.
Watch the register at final account. The variation account is usually the largest and most argued element of the final account. A complete, contemporaneous register is worth more at that point than any negotiating skill. For contractors doing this at scale, construction ERP software in the UAE holds the register against the cost structure rather than in a separate spreadsheet.
Part of our complete guide to ERP for construction.